Honoring Veterans Through Informed Homeownership As we approach Veterans Day on November 11, it’s a…
Down Payment Assistance and VA Loans: Explore Options
Buying a home can feel out of reach when the down payment and closing costs start adding up.
Down payment assistance programs may help eligible buyers cover upfront costs, while VA loans may allow eligible veterans, service members, and surviving spouses to purchase a primary residence with no down payment.
In this guide, I’ll explain how both options work, who may qualify, and what we should review before choosing a loan structure.
Key Takeaways
- Purpose: Down payment assistance can help with upfront homebuying costs, while VA financing offers eligible borrowers a no-down-payment option.
- Eligibility: Assistance programs commonly consider income, purchase price, property location, and homebuyer status; VA eligibility is based on qualifying military service.
- Costs: A VA loan may include a funding fee unless the borrower qualifies for an exemption, and assistance programs may include repayment conditions.
- Best For: These options may fit buyers who qualify for VA benefits or need help preserving funds for closing and homeownership expenses.
Quick Answers
- Is down payment assistance free money? Sometimes, but not always. Assistance may be structured as a grant, a forgivable second mortgage, a deferred loan, or a loan with monthly payments.
- Does a VA loan require a down payment? Eligible borrowers can often finance a home with no down payment, although a down payment may still make sense in certain situations.
- Can assistance help with closing costs? Some programs allow funds to be used for eligible closing costs, but permitted uses vary.
- Do I have to be a first-time buyer? Not always. Some programs require first-time homebuyer status, while others are available to repeat buyers.
- Does eligibility mean automatic approval? No. The borrower, property, loan, and assistance program must each meet the applicable guidelines.
I’m David Goldberg (NMLS# 728872), VP of Mortgage Lending with The Goldberg Mortgage Team. I help buyers in Northeast Ohio and nationwide compare financing options based on the full cost of the loan, not just the down payment.
I got into mortgage lending somewhat by accident after being laid off from a sales management job and answering a newspaper ad. I knew very little about mortgages then, but 24 years later, helping people finance a major investment is still what I enjoy most.
What Is Down Payment Assistance?
Down payment assistance, commonly called DPA, is financial help that may cover part of a qualified buyer’s down payment or eligible closing costs.
The money can come from a state or local housing agency, nonprofit organization, employer program, or another approved source. Each program sets its own rules.
Some assistance is available across a state. Other programs are tied to a county, city, or specific property location.
That can matter throughout Greater Cleveland. A program available for a property in Cuyahoga County may be different from one offered in Lake County, Geauga County, Summit County, Lorain County, or Medina County.
Common Types of Down Payment Assistance
| Assistance Type | How It Generally Works | What to Review |
|---|---|---|
| Grant | Funds may not need to be repaid when all program conditions are met. | Occupancy rules, income limits, and ongoing conditions. |
| Forgivable Second Mortgage | The balance may be forgiven over time if the borrower follows the program requirements. | Forgiveness period and what happens after a sale or refinance. |
| Deferred Second Mortgage | Monthly payments may not be required, but repayment can become due later. | Repayment triggers and lien requirements. |
| Repayable Second Mortgage | The assistance is repaid through scheduled monthly payments. | Payment amount, term, and effect on debt-to-income calculations. |
The word “assistance” doesn’t tell us whether the money must be repaid. That’s why I want a buyer to understand the written terms before using the program.
You can read more about our down payment assistance options, but availability and requirements should always be confirmed for the specific property and transaction.
Who May Qualify for Down Payment Assistance?
Eligibility varies, but programs often review several common factors:
- Household or qualifying income
- Property location
- Purchase price
- Credit history and credit score
- Debt-to-income ratio
- First-time homebuyer status
- Completion of an approved homebuyer education course
- Use of the property as a primary residence
- Buyer contribution requirements
A first-time homebuyer is commonly defined as someone who hasn’t owned a primary residence during the applicable lookback period. However, definitions and exceptions can vary by program.
Not every borrower fits neatly into the standard mortgage box. A buyer may have strong income but limited liquid savings. Another may have enough for a down payment but want to keep a reasonable emergency reserve after closing.
Those are different situations. They may call for different answers.
How VA Loans Work
A VA loan is a mortgage backed by the U.S. Department of Veterans Affairs and offered through approved private lenders.
The VA guaranty reduces part of the lender’s risk. That allows qualified borrowers to receive financing with features that commonly include no required down payment and no monthly private mortgage insurance.
VA loans are generally available to eligible veterans, active-duty service members, certain members of the National Guard or Reserve, and some surviving spouses. Eligibility depends on current VA rules and qualifying service history.
A Certificate of Eligibility, or COE, confirms that the VA recognizes the borrower’s eligibility. It doesn’t confirm final loan approval.
VA Loan Qualification Goes Beyond Eligibility
After confirming VA eligibility, the lender still reviews the complete mortgage application. That commonly includes:
- Credit history
- Stable and qualifying income
- Current monthly debts
- Residual income
- Assets needed for closing
- Occupancy plans
- The property appraisal and condition
VA residual income is the money remaining after certain monthly obligations and estimated living expenses are considered. It is an important part of VA underwriting and is different from the standard debt-to-income ratio.
The home must also meet VA property requirements. An appraisal provides an opinion of value and reviews the property against VA minimum property requirements, but it isn’t a substitute for a home inspection.
Can VA Financing and Assistance Work Together?
In some situations, yes.
A VA borrower may not need assistance for the down payment, but help with eligible closing costs could still be useful. Whether a particular assistance program can be combined with a VA loan depends on the rules of both programs.
The source of the funds matters. So does the assistance structure.
A second mortgage must generally meet the first mortgage lender’s requirements. Grants and other funds must be properly documented. Seller credits, lender credits, gifts, and assistance funds also have separate rules about how they can be used.
This is where I like to slow down. Let’s look at the whole picture.
Comparing Down Payment Assistance and VA Loans
| Feature | Down Payment Assistance | VA Loan |
|---|---|---|
| Primary Purpose | Helps eligible buyers with certain upfront costs. | Provides mortgage financing to borrowers with qualifying VA eligibility. |
| Down Payment | May cover part or all of the required amount, depending on the program. | Often allows no down payment, subject to eligibility and loan approval. |
| Geographic Limits | Often applies only in approved areas. | Available nationwide, subject to VA and lender guidelines. |
| Repayment | May be forgiven, deferred, or repaid, depending on the program. | The mortgage is repaid under its regular loan terms. |
| Occupancy | Primary residence occupancy is commonly required. | The home generally must be the borrower’s primary residence. |
Why the Lowest Upfront Cost Isn’t Always the Full Answer
Reducing the money due at closing can be helpful. But it’s only one part of the decision.
An assistance program may come with a different interest rate, a second lien, repayment conditions, or limits on refinancing. A VA loan may include a funding fee unless an exemption applies. Credits can also affect the loan’s pricing and structure.
Before you make that decision, let’s run the numbers.
I usually compare:
- Estimated cash needed at closing
- Principal and interest payment
- Property taxes and homeowners insurance
- Mortgage insurance, if applicable
- VA funding fee treatment, if applicable
- Second mortgage payments or future repayment
- Estimated funds remaining after closing
- How long the buyer expects to own the property
A conventional loan with 3% down, an FHA loan with a 3.5% minimum down payment, a VA loan with no down payment, and a loan paired with assistance can produce very different short-term and long-term costs.
Rates, fees, assistance availability, and qualification standards change. Current information should be verified before choosing a program.
My Process for Reviewing Your Options
1. Start With Eligibility
I first look at basic program eligibility. For VA financing, that includes the borrower’s COE and intended occupancy. For assistance, it may include income, homebuyer status, property location, and purchase price.
2. Review Income, Credit, Debts, and Assets
Eligibility for a program is only the starting point. I also review the borrower’s financial documentation to see how the proposed loan may fit the applicable underwriting guidelines.
Self-employed borrowers may need additional income analysis. Buyers receiving variable pay, commissions, bonuses, or rental income may also need more documentation.
3. Compare the Loan Structures
I prepare options showing the estimated payment, funds needed at closing, and important loan terms. If assistance includes another lien, I explain when that lien may need to be repaid.
4. Plan Before Shopping
Pre-approval planning can help identify documentation issues early. It can also show whether the target purchase price leaves enough room for taxes, insurance, maintenance, and other expenses.
5. Confirm the Program Before the Offer
Assistance funds can be limited, and guidelines may change. The property, contract, lender, and first mortgage must all work with the selected program.
I don’t want a buyer assuming funds are available based only on an old website or a conversation from several months ago. We confirm the current details.
Talk Through Your Scenario
If you’re considering down payment assistance or believe you may qualify for a VA loan, I’m happy to review the details with you.
You can call, text, or email The Goldberg Mortgage Team to compare options, discuss pre-approval planning, and understand the next steps. I’m based in Cleveland and work with borrowers throughout Northeast Ohio and nationwide.
Frequently Asked Questions
What happens to down payment assistance if I sell or refinance?
The answer depends on how the assistance is structured. A deferred or forgivable second mortgage may become due after a sale, refinance, transfer, or failure to meet occupancy requirements, so the program documents should be reviewed carefully.
Can I use a VA loan to buy an investment property?
VA financing generally requires the borrower to occupy the property as a primary residence. A qualifying multi-unit property may be possible when the borrower occupies one unit, subject to VA and lender requirements.
Can a self-employed buyer qualify for these options?
Yes, a self-employed buyer may qualify when the income can be documented under the applicable mortgage and assistance guidelines. The review commonly includes tax returns, business records, and other documents based on the borrower’s circumstances.
How long does it take to confirm VA eligibility?
A lender can often request the Certificate of Eligibility electronically, but timing varies when additional service records are needed. Obtaining the COE early can help prevent delays during pre-approval.
Can down payment assistance be used for a condominium?
It may be possible when the condominium, buyer, first mortgage, and assistance program all meet the required guidelines. Condominium approval standards vary by loan type and should be checked before the buyer makes an offer.
This is educational and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.
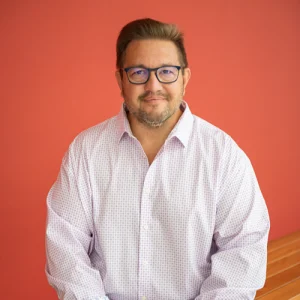
About the Author
David Goldberg
VP of Mortgage Lending at The Goldberg Mortgage Team · NMLS #728872
David Goldberg, a Cleveland based mortgage expert who helps first-time buyers, move-up homeowners, self-employed borrowers, real estate investors, Physicians, Veterans, and retirees find creative mortgage solutions throughout Northeast Ohio, Southeast Florida, and across the entire US. David has led The Goldberg Mortgage Team powered by Mutual of Omaha Mortgage since 2004.
Specializes in: Non-QM, Jumbo, Conventional
Licensed in: AL, AK, AZ, AR, CA, CO, CT, DE, FL, GA, HI, ID, IL, IN, IA, KS, KY, LA, ME, MD, MA, MI, MN, MS, MO, MT, NE, NV, NH, NJ, NM, NC, ND, OH, OK, OR, PA, RI, SC, SD, TN, TX, UT, VT, VA, WA, WV, WI, WY
Related Posts